Your Portfolio Is a One-Trick Pony, and the Circus Is Leaving Town
Market Sentiment
Volatile
What’s Happening at a Glance
- Investors are rotating away from concentrated mega‑cap tech into broader equities, real estate, and international markets.
- Energy and IT stocks have been both best and worst performers, illustrating the whipsaw nature of single‑theme bets.
- Diversification across sectors and regions is now viewed as the primary defense against unpredictable volatility.
- Central banks face an uncomfortable trade‑off between controlling inflation and preserving financial stability.
Market Summary
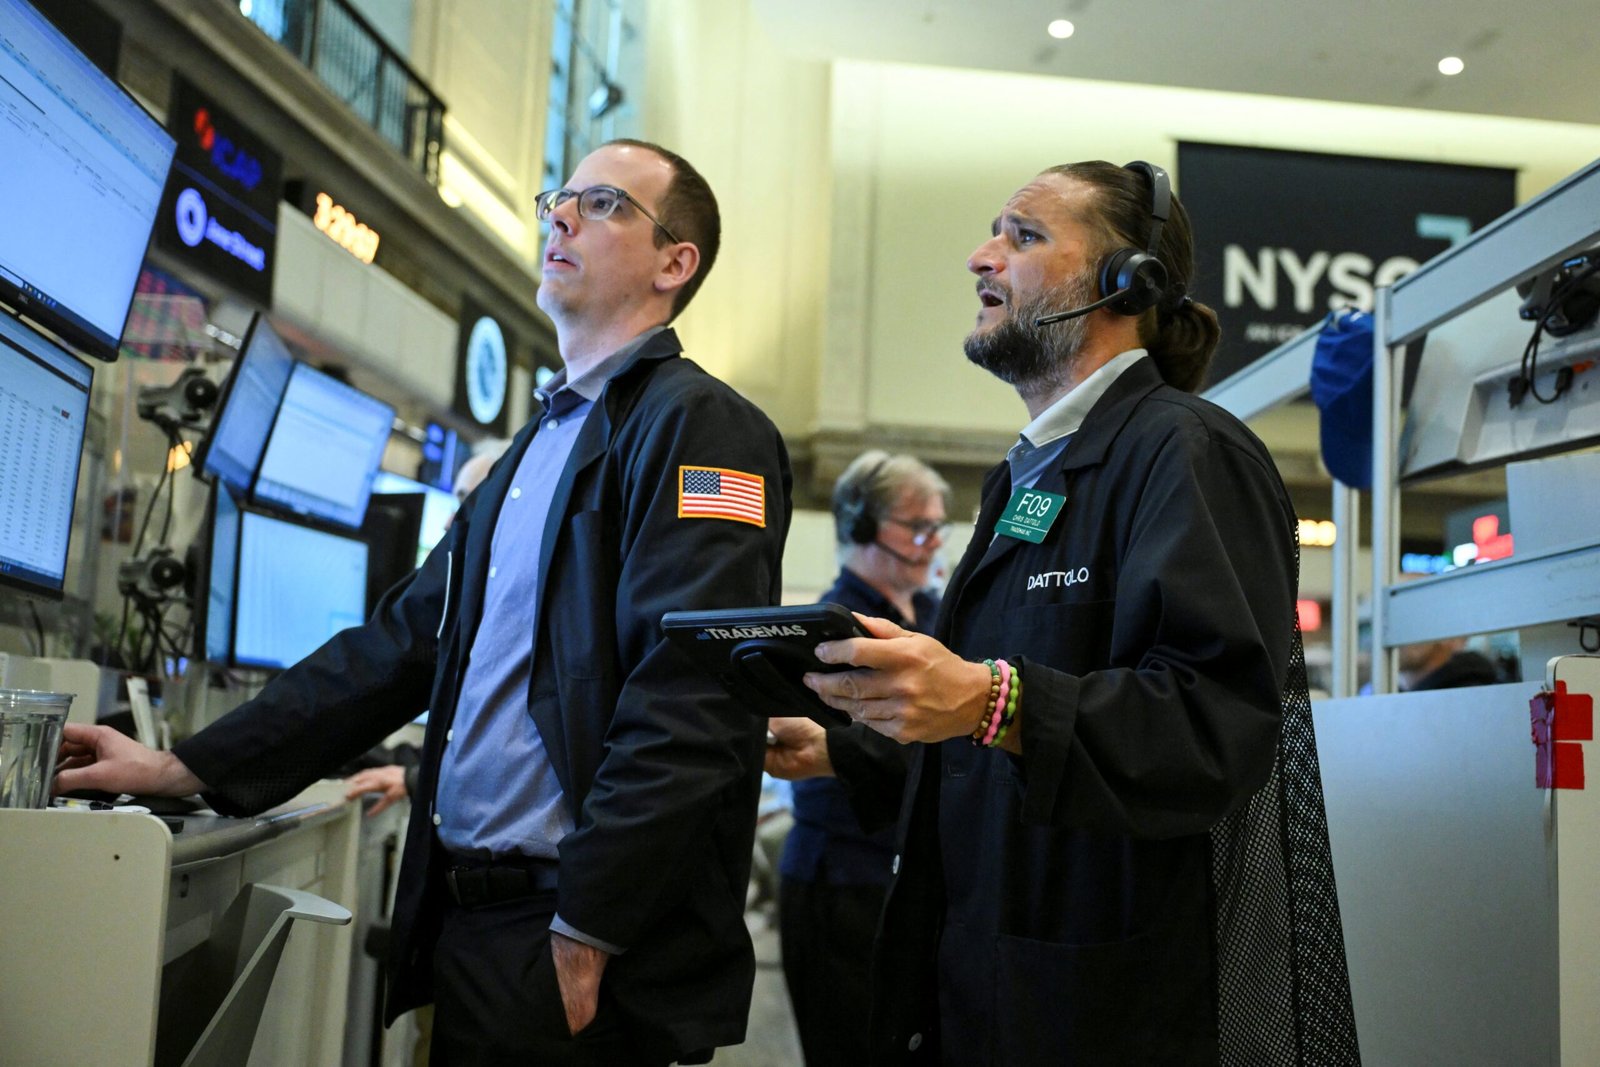
Six investors told CNBC that the biggest risk in 2025 is being too concentrated in the year’s biggest winners, especially the Magnificent Seven tech giants. They argue that U.S. exceptionalism is fading, debt levels in those companies are rising, and the market is rewarding breadth rather than size. In response, many are shifting from market‑cap‑weighted to equal‑weight strategies, adding real‑estate investment trusts, UK and Asian equities, and alternative assets that do not move in lockstep with stocks and bonds. The consensus is that diversification, not heroics, has been the winning play in a year where winners and losers have repeatedly swapped places.
Why This Is Happening
The current environment is shaped by several overlapping forces. First, the post‑pandemic surge in U.S. equity dominance has begun to reverse as valuations in the Magnificent Seven become stretched and their debt loads grow. Second, the massive AI infrastructure build‑out is capital‑hungry and inflationary at the margin, complicating central banks’ efforts to bring long‑term rates under control. Third, geopolitical tensions – particularly around the Strait of Hormuz – have added an oil price premium that conflicts with the disinflationary impact of strong corporate earnings. Together these factors create a market where single‑theme bets are punished and broad, flexible portfolios are rewarded.
Key Market Impact
- Major indices: S&P 500 and Nasdaq are seeing rotation away from mega‑caps toward small‑ and mid‑cap names.
- Sectors: data‑center industrials, energy, travel, and real‑estate trusts are gaining; consumer staples and healthcare have lagged.
- Interest rates: central banks are constrained, keeping long‑term rates volatile and bond markets uncertain.
- Consumer economy: higher oil prices and AI‑driven cost pressures may offset gains in real wages.
- Global ripple: flows into European industrials, Asian tech, and emerging‑market equities are increasing.
Impact on Americans
- 401(k)/retirement: diversified portfolios are less exposed to single‑stock drawdowns, protecting retirement savings.
- Consumer prices: energy and AI‑related costs could keep inflation from falling as quickly as hoped.
- Employment: rotation into industrials and services may create jobs outside the tech sector.
- Housing/mortgages: rising long‑term rates could pressure mortgage affordability.
- Savings/investments: holding too much cash or concentrated tech stocks risks lower real returns.
Affected Assets
- Stocks: broad equities, small‑caps, international shares, REITs.
- ETFs: equal‑weight SPY alternatives, international and sector‑specific funds.
- Bonds: long‑duration government bonds remain volatile; short‑term and inflation‑protected securities are favored.
- Crypto: limited direct impact, but may benefit as a diversifier.
- Commodities: oil and industrial metals see geopolitical and demand‑driven swings.
- Currencies: US dollar may weaken if rate differentials narrow; safe‑haven currencies could rally.