Inflation Cools to 3.4% – If You Ignore the $4 Gas, $5 Lettuce, and $600 Plane Tickets
Economic Sentiment
Mixed
What’s Happening at a Glance
- July CPI rose 3.4% year-over-year, down from 3.5% in June – the second straight annual decline
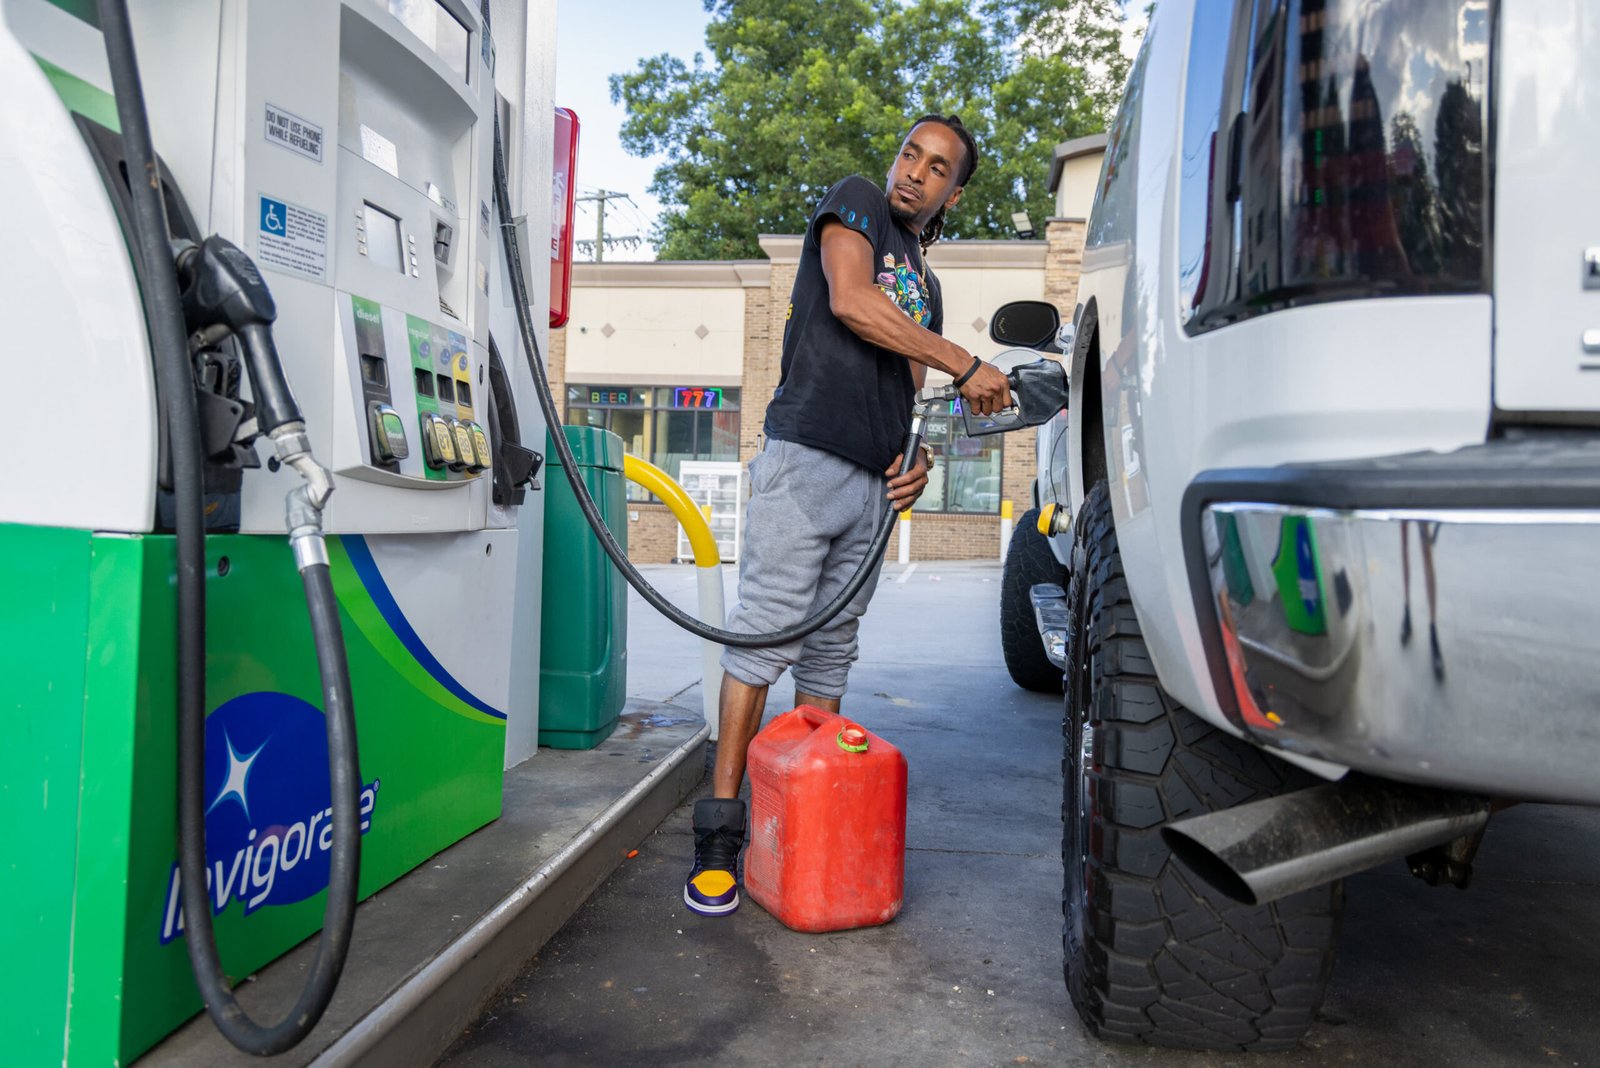
- Energy prices surged 14.7% annually, with gasoline up 24.6% ($4.04/gal national average) and fuel oil up 39.1%
- Core CPI (ex food/energy) moderated to 2.5%, with shelter, new vehicles, and apparel showing modest gains
- Fed keeps rates at 3.5–3.75% but signals possible hike; September possible, October more likely
Summary
Consumer prices ticked up in July after a June dip, but the annual inflation rate eased to 3.4% from 3.5%, marking the second consecutive monthly decline in the yearly pace. The headline improvement masks a sharp divide: energy costs remain the primary accelerant, driven by a hypothetical U.S.–Iran conflict that has sent crude oil and refined products soaring. Gasoline now averages $4.04 a gallon – up 90 cents from a year ago – and airline fares have jumped 25.5%. Food inflation is relatively contained at 3% overall, though meat prices are rising while eggs and dairy have softened. Cyclospora outbreaks have curbed lettuce demand, creating unusual produce volatility.
Core inflation, which the Fed watches closely, cooled to 2.5% – within striking distance of the 2% target. Shelter, new vehicles, and apparel all posted modest increases. Economists broadly called the report "benign" and "right down the strike zone," but cautioned that energy volatility could reverse progress. The Fed held rates steady last month at 3.5–3.75% but left the door open for another hike. Markets now see a September move as possible but lean toward October, with policymakers insisting on a "clear and lasting trend" before acting.
Why This Is Happening
The inflation dynamic is being driven by a supply-side energy shock rather than broad demand pressures. The hypothetical U.S.–Iran conflict has disrupted global oil markets, lifting crude and refined product prices. This feeds directly into gasoline, fuel oil, and airline fares – categories with high visibility and immediate household impact. Food prices are mixed: meat inflation persists from earlier herd reductions and feed costs, while egg prices have normalized after avian flu cycles. Lettuce prices are depressed by cyclospora-related demand destruction, not oversupply.
Core inflation's continued moderation reflects lagging shelter costs finally catching up to market rents, easing goods inflation as supply chains normalize, and the Fed's cumulative 525 basis points of tightening since 2022 finally transmitting through credit-sensitive sectors. The labor market remains tight but cooling gradually, keeping wage growth above pre-pandemic levels without triggering a wage-price spiral. Fiscal policy remains expansionary, but monetary restraint is the dominant force on aggregate demand.
Key Economic Impact
- Inflation: Headline stuck above target due to energy; core trending toward 2%
- Interest rates: Fed in wait-and-see mode; one more hike likely by year-end if energy persists
- Employment: Labor market cooling gradually; no sign of sharp upturn in layoffs
- Consumer spending: Holding up but rotating away from discretionary goods toward services and essentials
- Business activity: Input cost pressures easing outside energy; margins stabilizing
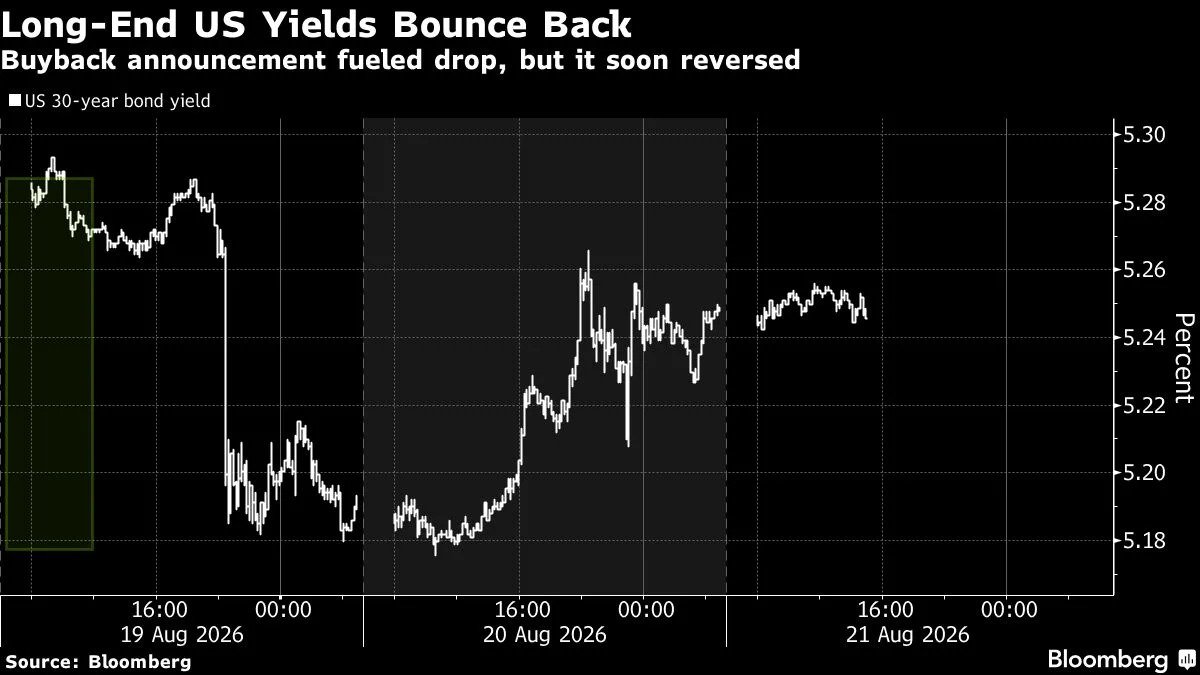
- Financial markets: Bonds pricing higher-for-longer; equities resilient but sensitive to oil headlines
Impact on People
- Household budgets: Gas and airfare eating into discretionary income; grocery bills mixed but manageable
- Jobs: Hiring slowing, layoffs low; job-switching premium fading
- Wages: Real wages positive for first time in two years as nominal growth outpaces inflation
- Housing: Shelter inflation sticky; rents plateauing but ownership costs high due to rates
- Borrowing costs: Mortgage rates near 7%; auto loans, credit cards at cycle highs
- Everyday expenses: Fill-ups and flights hurt; meat and lettuce volatile; used cars, electronics cheaper
Key Economic Indicators
- CPI: 3.4% headline, 2.5% core (YoY)
- PCE: Likely similar trajectory; Fed's preferred gauge
- GDP: Q2 growth ~2.4%; consumer resilience offsetting manufacturing weakness
- Unemployment: 3.6% – near historic lows but rising slowly
- Wage growth: ~4.4% annually – cooling but above inflation
- Retail sales: Moderating; control group sales flat in recent months
- Consumer confidence: Divergent – present situation strong, expectations fragile
Future Outlook
The path forward hinges on energy. If the Iran conflict de-escalates or global supply adjusts, headline inflation could drop below 3% by year-end, giving the Fed cover to hold rates steady and eventually cut in 2025. If oil stays elevated or spikes further, the Fed may hike once more in October, keeping financial conditions restrictive longer. Core inflation's trajectory suggests the underlying trend is favorable, but the Fed has emphasized it needs "convincing evidence" – not just one or two good prints. Consumers face a split reality: real income gains are returning, but every trip to the pump or airport reminds them the inflation war isn't over.