Treasury’s ‘Double‑Size’ Bond Buyback Fails to Quiet Yields, Which Stay Sky‑High
Market Sentiment
Volatile
What’s Happening at a Glance
- 30‑year Treasury yield jumped to 5.34%, highest since 2007, as inflation worries and a $40 trillion debt load mount.
- Treasury announced a surprise “double‑size” buyback of long‑dated bonds, briefly pulling yields lower before they rebounded.
- Corporate AI‑focused debt issuance is draining demand from Treasuries, adding further upward pressure on yields.
- Higher yields translate to pricier mortgages, car loans, credit cards and tighter household budgets.
Market Summary
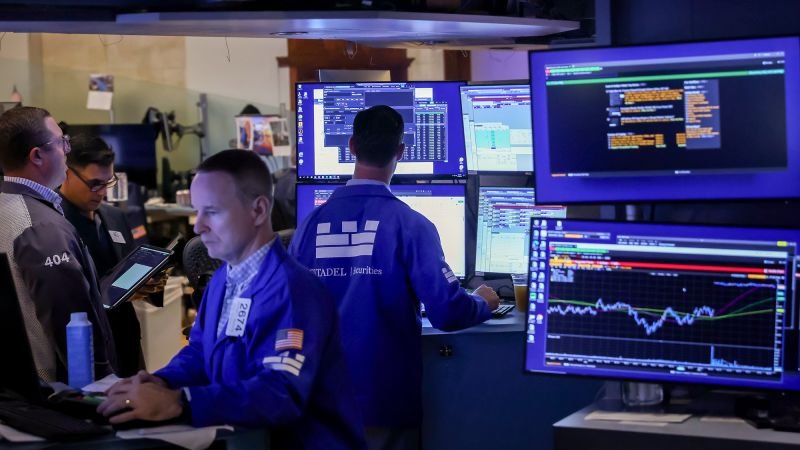
The bond market endured a turbulent week as the 30‑year Treasury yield surged to 5.34%, its highest level since before the 2008 financial crisis. The spike reflects persistent inflation concerns, a record‑high $40 trillion national debt, and a 6%‑of‑GDP fiscal deficit that fuels investor demand for higher compensation. In an attempt to reassure markets, the Treasury unveiled an unusually large buyback of older long‑dated bonds, promising to “at least double” its usual repurchase volume. While the announcement momentarily dragged yields lower, they resumed climbing the next day, settling around 5.2% for the 30‑year and 4.7% for the 10‑year benchmark. Compounding the pressure, tech giants are flooding the market with new AI‑related corporate debt, competing for the same pool of bond buyers and effectively pulling demand away from Treasuries. Analysts warn that without a substantive reduction in the deficit – through spending cuts or tax reforms – yields are likely to stay elevated, keeping borrowing costs high for governments, businesses, and consumers.
Why This Is Happening
Persistent inflation and a ballooning federal deficit (about 6% of GDP) have pushed investors to demand higher yields for holding U.S. debt. The national debt recently crossed $40 trillion, quadrupling since 2008, while the Treasury’s usual modest buyback program was suddenly expanded, an atypical move that caught markets off guard. Simultaneously, large tech firms are issuing substantial new debt to fund AI development, creating competition for the same bond buyers and reducing demand for Treasuries. The administration has hinted at future fiscal consolidation – budget cuts and tax increases – but no concrete plan has yet materialized, leaving the underlying fiscal imbalance unresolved. Consequently, Treasury yields remain high despite the brief buyback intervention, underscoring the market’s dominance over policy actions.
Key Market Impact
- Affected stock sectors: financials (banks and mortgage lenders), consumer discretionary (housing), technology (AI debt issuers).
- Major indices: S&P 500, Dow Jones, Nasdaq – experiencing heightened volatility.
- Interest rates / bonds: 30‑year Treasury yield ~5.2%, 10‑year ~4.7%; higher benchmark rates for mortgages, auto loans, and other consumer credit.
- Consumer economy: rising mortgage and loan rates squeeze household budgets, dampening spending and home‑ownership affordability.
- Global ripple effects: higher U.S. yields can strengthen the dollar, pressure emerging‑market debt, and influence global bond market dynamics.
Impact on Americans
- 401(k)/retirement impact: bond fund values may decline amid higher yields, though new fixed‑income holdings could offer better returns; overall portfolio volatility persists.
- Consumer prices: elevated borrowing costs can feed into inflation, especially in housing and credit‑driven spending.
- Employment: tighter credit and reduced housing activity may slow job growth in construction, retail, and related services.
- Housing/mortgages: mortgage rates staying above 6% keep homeownership out of reach for many, cooling the housing market.
- Savings/investments: savers benefit from higher yields on new bonds, but existing bond‑focused investments suffer price declines.
Affected Assets
- Stocks: financials, mortgage lenders, consumer discretionary, AI‑focused tech firms.
- ETFs: Treasury bond ETFs (e.g., TLT, IEF), mortgage REIT ETFs, AI‑themed equity ETFs.
- Bonds: long‑dated U.S. Treasury bonds, corporate AI debt, high‑yield corporate bonds.
- Crypto: risk‑off sentiment may exert downward pressure.
- Commodities: indirect effect via a stronger dollar potentially weighing on commodity prices.
- Currencies: U.S. dollar likely strengthens against emerging‑market currencies.